
At UK Moneyman, we provide mortgage advice to customers across England, Scotland and Wales, helping with everything from buying a first home and remortgaging to more specialist borrowing needs.
Our experienced mortgage advisors take the time to understand your circumstances, explain your options clearly and find suitable mortgage deals from a wide range of lenders.
Led by Malcolm Davidson, we’ve been providing reliable, personal mortgage advice since 2009, with a focus on making the process straightforward and keeping you informed from start to finish.

At UK Moneyman, we provide mortgage advice for first-time buyers, home movers and buy-to-let investors, helping customers understand their borrowing options when purchasing a property.
We work with customers across England, Scotland and Wales, from those buying their first home to experienced homeowners looking to move.
Our mortgage advisors also have experience with purchases involving shared ownership, self-employed applicants, adverse credit and borrowing circumstances that may fall outside standard high street lending criteria.
We understand that different customers have different priorities. Some want to establish how much they can borrow before searching for a home, while others have found a property and need to understand their mortgage options.
With experience in mortgage advice since 2009, we understand how different lenders approach property purchases and the circumstances that can affect eligibility.
Our focus is on finding suitable mortgage options that reflect your financial position and the property you want to buy.
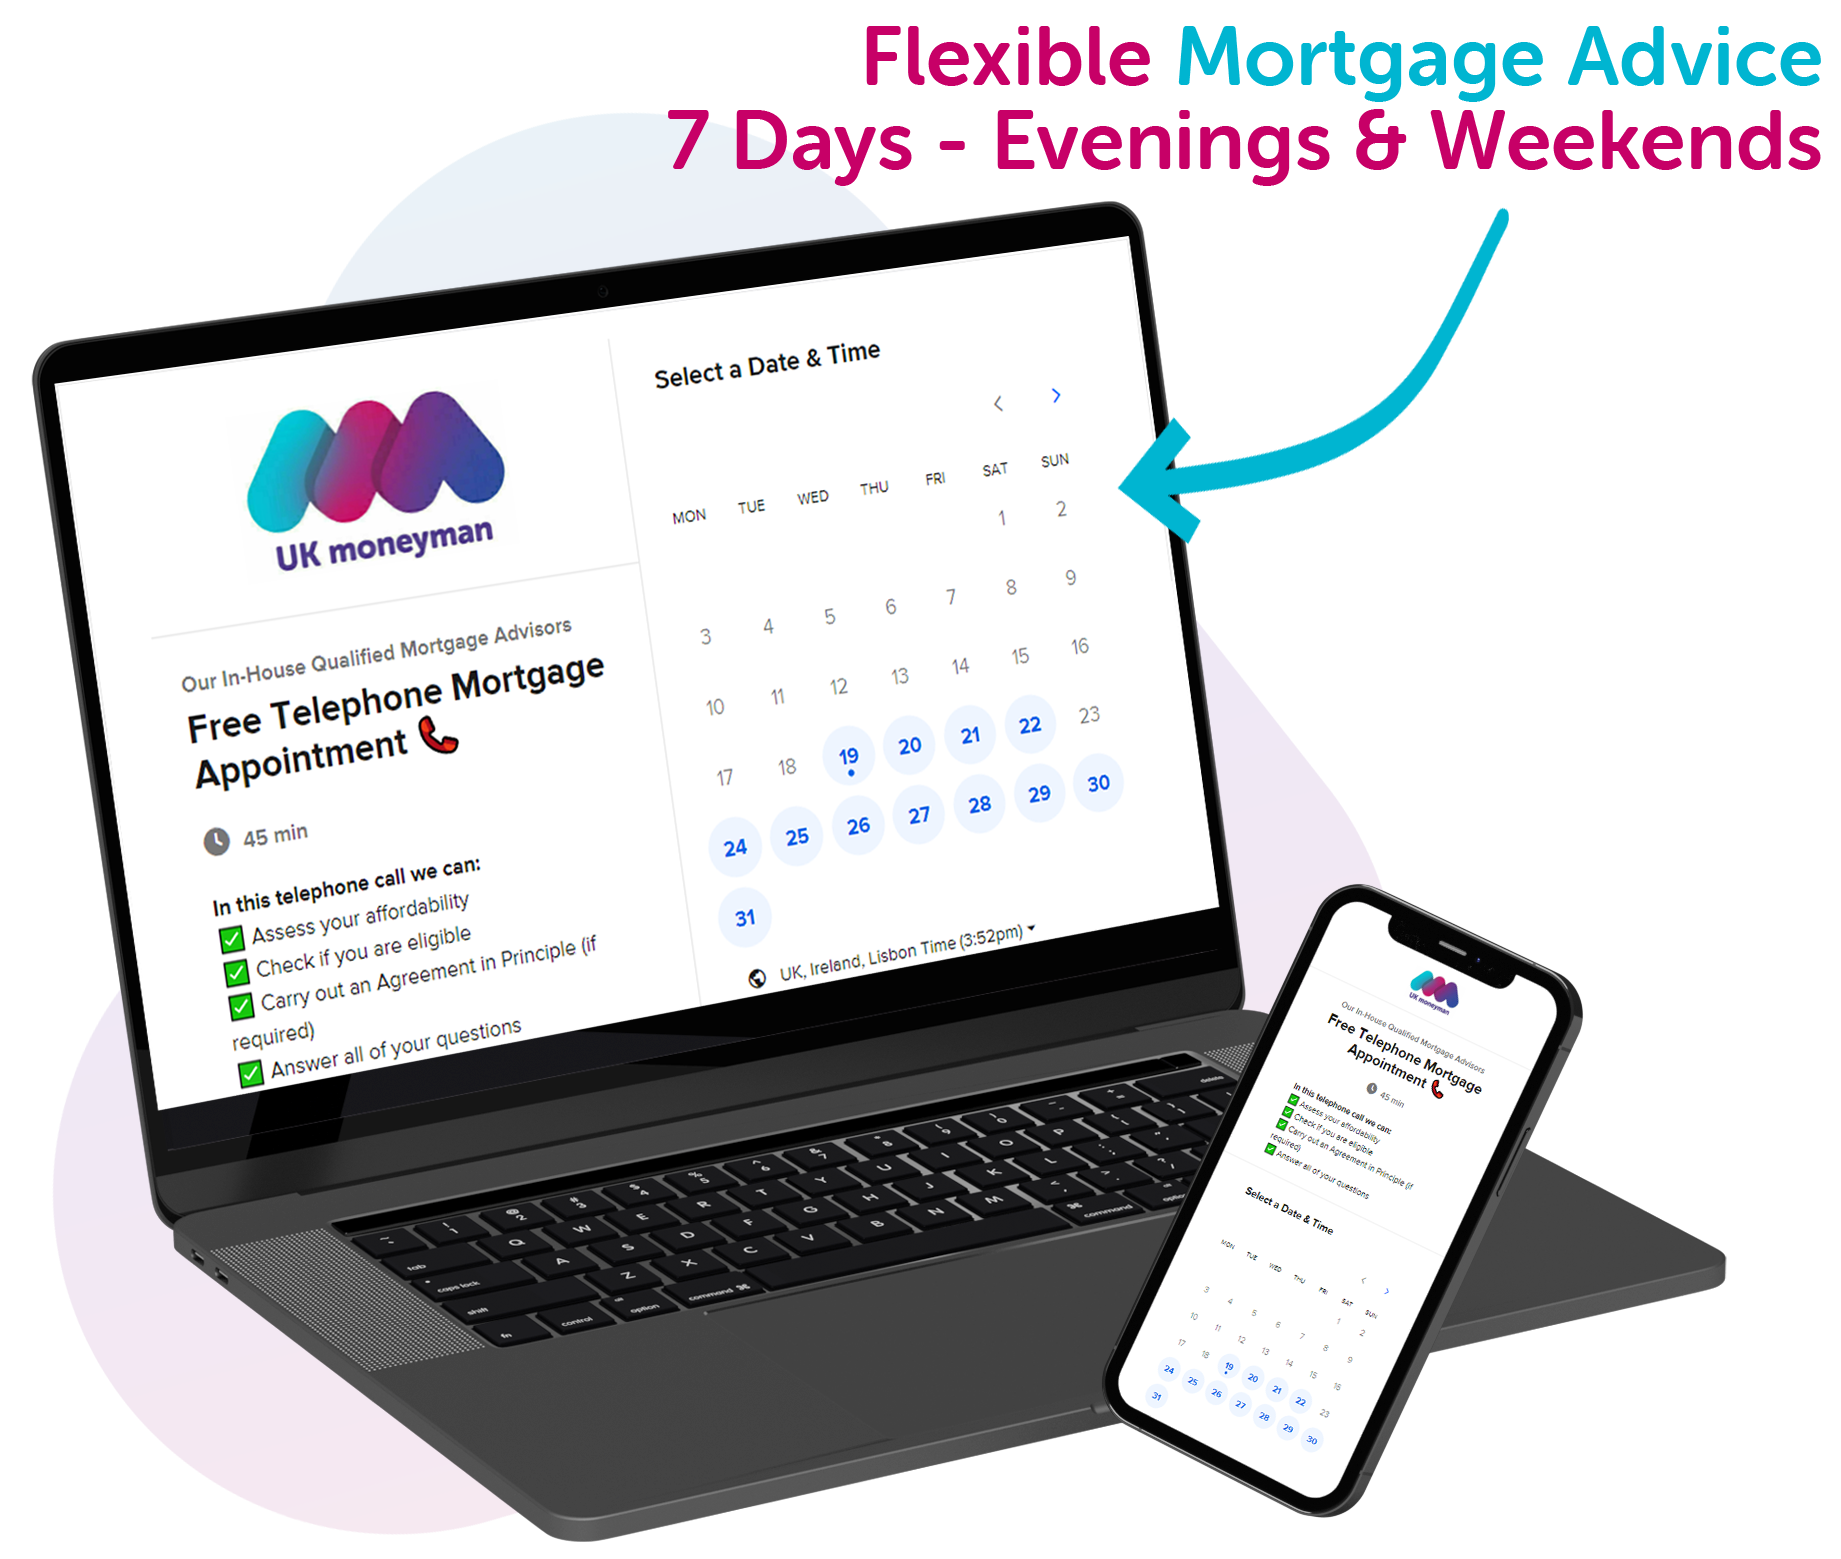
Our purchase mortgage process begins with a free initial appointment, where we’ll establish your borrowing needs, available deposit and financial circumstances.
We can typically provide an Agreement in Principle within 24 hours of your initial appointment, giving you an indication of how much a lender may be prepared to offer.
Once you’re ready to proceed with a property, we’ll compare suitable mortgage deals, explain the costs involved and recommend an option based on your circumstances.
We’ll then prepare and submit your application, making sure the lender receives the relevant income evidence, deposit information and supporting documents.
Your dedicated case manager will keep you updated as the application progresses, including any additional lender requests and the mortgage valuation.
Once your mortgage offer has been issued, we’ll remain in contact as the purchase moves towards completion, alongside the legal work being handled by your conveyancer.
Speak to an Advisor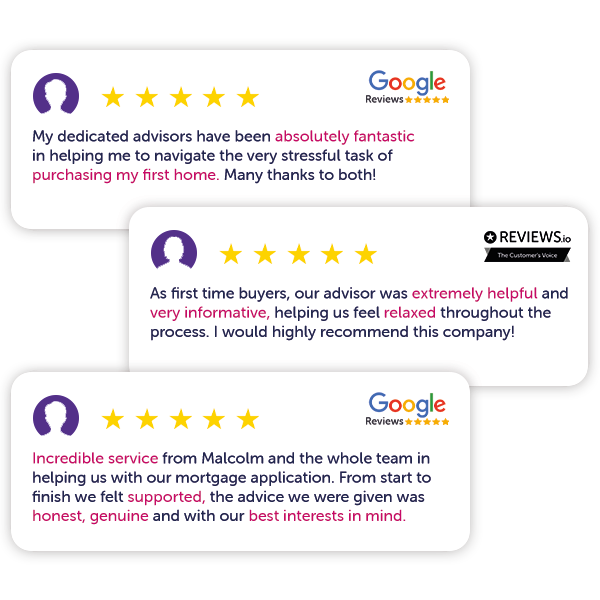

Remortgaging gives homeowners an opportunity to review their existing mortgage, secure a new interest rate or make changes to their borrowing.
At UK Moneyman, we provide remortgage advice for customers approaching the end of a fixed-rate deal, particularly those wanting to avoid moving onto their lender’s standard variable rate.
We also work with homeowners looking to release equity for home improvements, consolidate debts or help family members with a property purchase.
Changes to employment, income or credit history can affect the options available since the original mortgage was arranged.
Some homeowners may also benefit from remaining with their existing lender rather than moving elsewhere, depending on the rates available and the changes they want to make.
Our experience covers straightforward remortgages and more specialist circumstances, including applications involving self-employed income, adverse credit and additional borrowing.
We start by looking at your existing mortgage, including its outstanding balance, current interest rate and when your deal is due to end.
This helps establish when you can switch without incurring an early repayment charge and whether there are any costs associated with leaving your current lender.
We’ll consider the deals available through your existing lender alongside remortgage products elsewhere, comparing the interest rates, fees and overall cost of each option.
If you’re looking to borrow more, we’ll also establish how the additional borrowing affects your repayments and the amount of equity remaining in your property.
Once a suitable option has been agreed, we’ll arrange the remortgage application and coordinate the requirements for moving to the new deal.
Where possible, we’ll aim to time the switch so your new mortgage starts as your existing deal ends, reducing the likelihood of spending unnecessary time on a standard variable rate.
Book Your Mortgage Review!
Getting a mortgage over 50 can involve different considerations, particularly if you’re approaching retirement, already receiving pension income or planning to continue borrowing into later life.
At UK Moneyman, we work with customers looking to purchase a property, remortgage an existing home or release money from their property as their circumstances change.
Your options may include a standard residential mortgage, a retirement interest-only mortgage or equity release through a lifetime mortgage, depending on your age, income and borrowing needs.
Some homeowners want to reduce their monthly payments, while others are looking to move home, repay an existing mortgage or access funds for improvements.
Retirement does not automatically prevent you from getting a mortgage. Lenders can consider different forms of retirement income, although their requirements and maximum mortgage terms vary.
Our team has experience with mortgages for older borrowers, including specialist later-life lending, helping customers understand the arrangements available and their longer-term implications.
An age 50+ mortgage review begins by understanding your current financial position and how you expect it to change over the coming years.
For someone approaching retirement, we’ll consider their existing earnings, expected pension income and whether the proposed mortgage will remain affordable after they stop working.
If you’re already retired, the assessment may focus on pension payments, other eligible income and the mortgage arrangements available for your circumstances.
We’ll explain the differences between relevant options, including how repayments work, when the mortgage needs to be repaid and what happens to the outstanding balance over time.
Lifetime mortgages work differently from standard residential borrowing, so we’ll also explain how interest can accumulate and the potential effect on the equity remaining in your home.
Where appropriate, family members can be involved in discussions, particularly when the decision could affect future inheritance or longer-term plans.
The aim is to establish which options meet your needs now while considering how the mortgage may affect your finances in the future.
Speak to an Over 50s Advisor Today
Mortgage protection and personal insurance can provide financial support if illness, injury or death affects your household’s income or ability to meet financial commitments.
At UK Moneyman, we provide advice on life insurance, critical illness cover, income protection and family income benefit.
These policies serve different purposes. Life insurance can provide a payment following death, while critical illness cover may pay a lump sum if you are diagnosed with a specified serious condition covered by the policy.
Income protection can provide regular payments if illness or injury prevents you from working, subject to the policy terms.
Family income benefit is another form of life cover that can provide regular payments to your beneficiaries for the remaining policy term, rather than one lump sum.
The appropriate protection depends on your personal circumstances, including your mortgage, income, dependants and any existing cover through employment or other arrangements.
Our protection advice starts with understanding the financial responsibilities you want to protect and what would happen if your household experienced a loss of income or other unexpected change.
We’ll consider your mortgage balance, monthly commitments, dependants and any existing insurance policies or employee benefits.
This helps identify where you may already have suitable cover and where there could be gaps.
We can explain the differences between available protection policies, including the type of payment they provide, how long cover lasts and the circumstances in which a claim may be made.
The cost of insurance depends on several factors, including the level of cover, policy term, age, health and other underwriting considerations.
Before proceeding, we’ll explain the relevant exclusions, limitations and any information the insurer needs to assess your application.
This allows you to choose protection that reflects your household’s financial needs, rather than simply adding insurance because you’re arranging a mortgage.
Speak to an Advisor
Your home may be repossessed if you do not keep up repayments on your mortgage.
There may be a fee for mortgage advice. The fee is up to 1% but a typical fee is £495.
Our Customers Love Us
 218 5 Star Reviews
Harry w
Used UK moneymans services three times now. The staff are all professional, friendly, informative and speedy with their communications whether that be calls or emails. Takes so much stress out of mortgage hunting. Would recommend to anyone
17 Nov 2026

K
Dinah & Lizzie, Were great. Got us a high street lender at a great rate, And for being self employed we didn't think this was possible. so thank you!
12 Nov 2026
Joseph Harros
As first-time buyers, we had very little knowledge of the mortgage process and found it quite daunting, especially with rising interest rates and uncertainty in the property market. We’re extremely grateful to Dinah and Jo for their support and would highly recommend UK Moneyman to any first-time buyer looking for a professional, knowledgeable and supportive mortgage broker.
29 Oct 2026
Jade Wilmot
As first-time buyers, we had very little knowledge of the mortgage process. We changed properties along the way, and our circumstances made the mortgage process more complex than we initially expected. Dinah and Jo were absolutely brilliant throughout. We would definitely recommend UK Moneyman to anyone looking to set up a mortgage.
29 Oct 2026
Diane A
First class service. Jason and Lizzie helped me immensely getting a good mortgage quickly when I found myself separated. They pulled out all the stops and even spoke to me after hours. Excellent and would highly recommend. I can’t thank them enough. I now have my dream home
28 Oct 2026
Chloe Gathergood
Paula and Jason have been so helpful in getting our first mortgage sorted. They were quick to answer any questions and very helpful with their advice. Thank you very much
23 Oct 2026
Rebecca Joy
Leo and Lizzi were exceptionally helpful. Leo gave us great advise, not just on products available, but on things like bidding on properties, whether we were likely to be approved for more complicated properties etc. Lizzi was very communicative and thorough in processing our application, and after our first sale fell through we didn't hesitate to use UK Moneyman again. Thanks so much to Leo and Lizzi!
15 Oct 2026
Callum Kennedy
Very helpful and informative. Made the process as easy as possible. Would recommend to other
14 Oct 2026
Barry Hall
I had a financial issue that I thought was pretty unique to myself. The help and solution to my financial question has been exceptional in every step of the way. A big thank you to Warren and Joe for all of your patience and technical expertise.
14 Oct 2026
Megan Whitlock
The team working with my profile were amazing, I was in constant communication with them, if I emailed and rang someone responded quickly and they were able to secure my mortgage within 6 weeks from my initial meeting which saved me a lot of messing around and stress. Great service thank you
14 Oct 2026


Read our Reviews

UKmoneyman is a trading name of UKMM Limited, which is an appointed representative of Mortgage Advice Bureau (Derby) Limited, who are authorised and regulated by the Financial Conduct Authority.
UKMM Limited is Registered in England, No. 16541342 | Registered Address: Capital House, Pride Place, Pride Park, Derby, England, DE24 8QR.
© UKmoneyman 2009–2026





UKmoneyman is a trading name of UKMM Limited, which is an appointed representative of Mortgage Advice Bureau (Derby) Limited, who are authorised and regulated by the Financial Conduct Authority.
UKMM Limited is Registered in England, No. 16541342 | Registered Address: Capital House, Pride Place, Pride Park, Derby, England, DE24 8QR.
© UKmoneyman 2009–2026

We value your privacy
This website uses cookies. If you continue to use the site, we will assume that you agree with our use of cookies.


