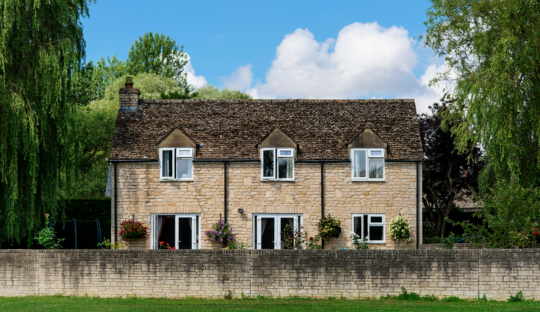
If you’re not ready to sell your current home, let-to-buy may offer another way to move:
A let-to-buy mortgage allows homeowners to keep their current property when moving to a new home.
Rather than selling your existing property, you rent it out and purchase another property to live in.
This can be an option for homeowners who have built up equity in their property and would prefer to retain ownership instead of selling.
Common reasons for considering let-to-buy include moving for work, needing more space, relocating with family, or wanting greater flexibility before selling a property.
Unlike a standard home move, a let-to-buy arrangement involves both your current property and your onward purchase.
As a result, lenders will assess a range of factors, including your equity position, mortgage affordability and the suitability of the property being rented out.
Every situation is different, which is why let-to-buy mortgages are typically tailored around your circumstances, plans and borrowing requirements.
Our Customers Rate us 4.9/5


A let-to-buy mortgage usually involves two separate mortgages.
The first is secured against your current property, which will be rented out to tenants.
The second is a residential mortgage for the property you plan to move into.
Many homeowners use equity from their existing property towards the deposit for their onward purchase.
Lenders will then assess factors such as the expected rental income, the amount of equity available and your affordability for the new residential mortgage.
Timing can be an important part of a let-to-buy application, particularly if both transactions are taking place at the same time.
Each lender has its own criteria, which is why the available options can vary depending on your circumstances.
Appointments 7 Days a Week

Every lender has its own approach to let-to-buy mortgages, though there are several factors that are commonly assessed during the application process.
Lenders will usually consider the amount of equity available in your current property, the expected rental income and your affordability for the residential mortgage on your new home.
They may also review your credit history, income and existing financial commitments.
The deposit for your onward purchase often comes from equity built up in your current property, though the requirements can vary depending on the lender and your circumstances.
As let-to-buy involves both a rental property and a residential purchase, it can be more complex than a standard home move.
Understanding your options early can help identify the most suitable route before you start searching for your next property.
Explore 1000s of Mortgage Options

Our Customers Love Us
 218 5 Star Reviews
Harry w
Used UK moneymans services three times now. The staff are all professional, friendly, informative and speedy with their communications whether that be calls or emails. Takes so much stress out of mortgage hunting. Would recommend to anyone
17 Nov 2026

K
Dinah & Lizzie, Were great. Got us a high street lender at a great rate, And for being self employed we didn't think this was possible. so thank you!
12 Nov 2026
Joseph Harros
As first-time buyers, we had very little knowledge of the mortgage process and found it quite daunting, especially with rising interest rates and uncertainty in the property market. We’re extremely grateful to Dinah and Jo for their support and would highly recommend UK Moneyman to any first-time buyer looking for a professional, knowledgeable and supportive mortgage broker.
29 Oct 2026
Jade Wilmot
As first-time buyers, we had very little knowledge of the mortgage process. We changed properties along the way, and our circumstances made the mortgage process more complex than we initially expected. Dinah and Jo were absolutely brilliant throughout. We would definitely recommend UK Moneyman to anyone looking to set up a mortgage.
29 Oct 2026
Diane A
First class service. Jason and Lizzie helped me immensely getting a good mortgage quickly when I found myself separated. They pulled out all the stops and even spoke to me after hours. Excellent and would highly recommend. I can’t thank them enough. I now have my dream home
28 Oct 2026
Chloe Gathergood
Paula and Jason have been so helpful in getting our first mortgage sorted. They were quick to answer any questions and very helpful with their advice. Thank you very much
23 Oct 2026
Rebecca Joy
Leo and Lizzi were exceptionally helpful. Leo gave us great advise, not just on products available, but on things like bidding on properties, whether we were likely to be approved for more complicated properties etc. Lizzi was very communicative and thorough in processing our application, and after our first sale fell through we didn't hesitate to use UK Moneyman again. Thanks so much to Leo and Lizzi!
15 Oct 2026
Callum Kennedy
Very helpful and informative. Made the process as easy as possible. Would recommend to other
14 Oct 2026
Barry Hall
I had a financial issue that I thought was pretty unique to myself. The help and solution to my financial question has been exceptional in every step of the way. A big thank you to Warren and Joe for all of your patience and technical expertise.
14 Oct 2026
Megan Whitlock
The team working with my profile were amazing, I was in constant communication with them, if I emailed and rang someone responded quickly and they were able to secure my mortgage within 6 weeks from my initial meeting which saved me a lot of messing around and stress. Great service thank you
14 Oct 2026
Your home may be repossessed if you do not keep up repayments on your mortgage.
There may be a fee for mortgage advice. The fee is up to 1% but a typical fee is £495.
More on Let to Buy Mortgages
We're flexible to work around your busy schedule, we work beyond the general 9-5 in order to be there when you need us.
You won't have to pay us until we do something! We only ask for payment once we get results.
You'll always have the same case manager to help work alongside you throughout the entire process.
Sometimes new landlords need additional support. We’ll be to support you throughout the entire process.
Our team will recommend suitable insurance products to ensure you can stay in your home should you become seriously ill and unable to work.
Our mortgage advisors will search the market for the most suitable let to buy mortgage to match your current circumstances, saving you time and money.
Having been in the industry for over 20 years, we have helped many customers obtain a let to buy mortgage. There's hardly a situation that we haven't come across before.
Throughout the mortgage process, we will help you overcome any hurdles you encounter like issues with property surveys and down valuation.



Read our Reviews

UKmoneyman is a trading name of UKMM Limited, which is an appointed representative of Mortgage Advice Bureau (Derby) Limited, who are authorised and regulated by the Financial Conduct Authority.
UKMM Limited is Registered in England, No. 16541342 | Registered Address: Capital House, Pride Place, Pride Park, Derby, England, DE24 8QR.
© UKmoneyman 2009–2026





UKmoneyman is a trading name of UKMM Limited, which is an appointed representative of Mortgage Advice Bureau (Derby) Limited, who are authorised and regulated by the Financial Conduct Authority.
UKMM Limited is Registered in England, No. 16541342 | Registered Address: Capital House, Pride Place, Pride Park, Derby, England, DE24 8QR.
© UKmoneyman 2009–2026

We value your privacy
This website uses cookies. If you continue to use the site, we will assume that you agree with our use of cookies.